Legal & Due Diligence
Mortgage Closing Costs: How Much Cash Do You Need Out of Pocket?
Mar 15, 2019 · 5 min
For most people, buying property is a rare event. Taking part in one or two real estate transactions in a lifetime does not build deep knowledge of the process. There are many documents to sign, confusing new jargon, and plenty of fast-talking people from agents to brokers. Beyond the mortgage amount, nearly everything else falls under “closing costs.” Keeping an eye on those costs shows you where your money goes and can even save you a few hundred dollars.
Closing costs: what are they?
The phrase “closing costs” is shorthand for the combined total of several dozen potential expenses tied to buying and financing a home. They can be classified as “recurring” and “one-time,” and they are additional to your down payment.
Recurring expenses
Recurring expenses are paid not just at closing but monthly after the purchase. They include property taxes, homeowner’s insurance, HOA fees and - if your down payment is under 20% of the purchase price - private mortgage insurance (PMI). Part of these costs may be paid up front at purchase (for example, an insurance year and a portion of property taxes).
One-time expenses
One-time expenses are also settled at closing. They can include:
- a fraction of a percent of the mortgage paid to receive lower monthly payments (points)
- the loan origination fee - the lender’s profit
- a set of loan fees that may include the appraisal fee, the credit-report fee, tax service fees, wire-transfer charges, your attorney’s fee, recording fees with government offices, and so on
- any home inspections, such as termite, radon and others
- the flood-zone determination, to check whether the property sits in a flood-prone area
- title insurance on the home
Many other incidental costs can appear: courier and delivery, recording fees, transfer taxes and an additional home warranty.
How much do they cost?
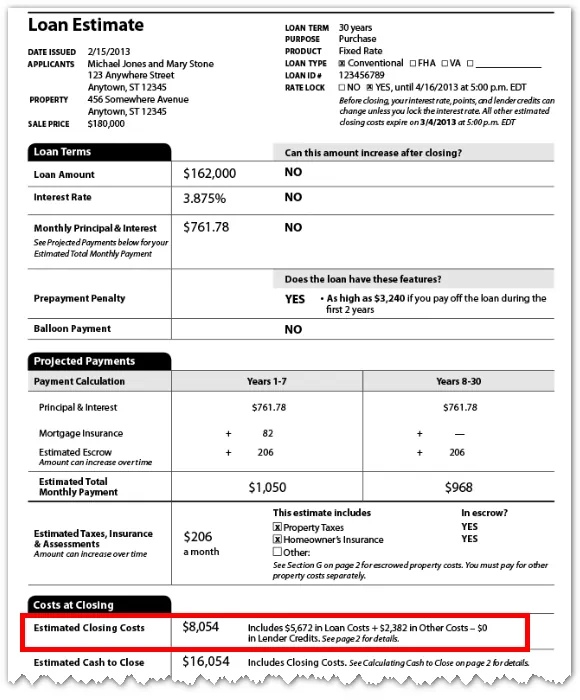
Fees vary widely depending on the lender, the geographic location and the home price. In the Raleigh area, plan on a range of $4,000–7,000. Before buying, ask your bank or mortgage broker for a “Loan Estimate,” which lists the approximate closing costs. You can also request a breakdown and challenge any inflated or unusual charges.
Questions & answers
How much cash do I need beyond the down payment?
Plan 2-5% of the price in closing costs - lender fees, title, insurance, taxes and prepaids - tracked line by line on the Loan Estimate. On a $400,000 home that is $8,000-$20,000 before the down payment.
Can the seller pay my closing costs?
Seller credits toward closing costs are negotiable and common, within lender limits by loan type. In competitive offers, weigh credits against price - I model both.
What is PMI and when does it drop off?
Private mortgage insurance applies below 20% down on conventional loans. It falls off automatically at 78% of the original value (or by request around 80% with a current appraisal and good history).